


NFP Preview: Will US Jobs Rebound After September's 29,000?
BY Ahmed Osama
|November 4, 2026The US nonfarm payrolls report for October is due at 13:30 UTC on Friday 6 November. After the economy added just 29,000 jobs in September, forecasts point to a modest recovery to around 65,000, with unemployment expected to stay at 4.2%. Coming just over a week after the Federal Reserve held rates and kept the door open to a December rise, the NFP report could move the US dollar, gold and EUR/USD sharply.
NFP report in brief
- The October nonfarm payrolls report is due at 13:30 UTC on Friday 6 November.
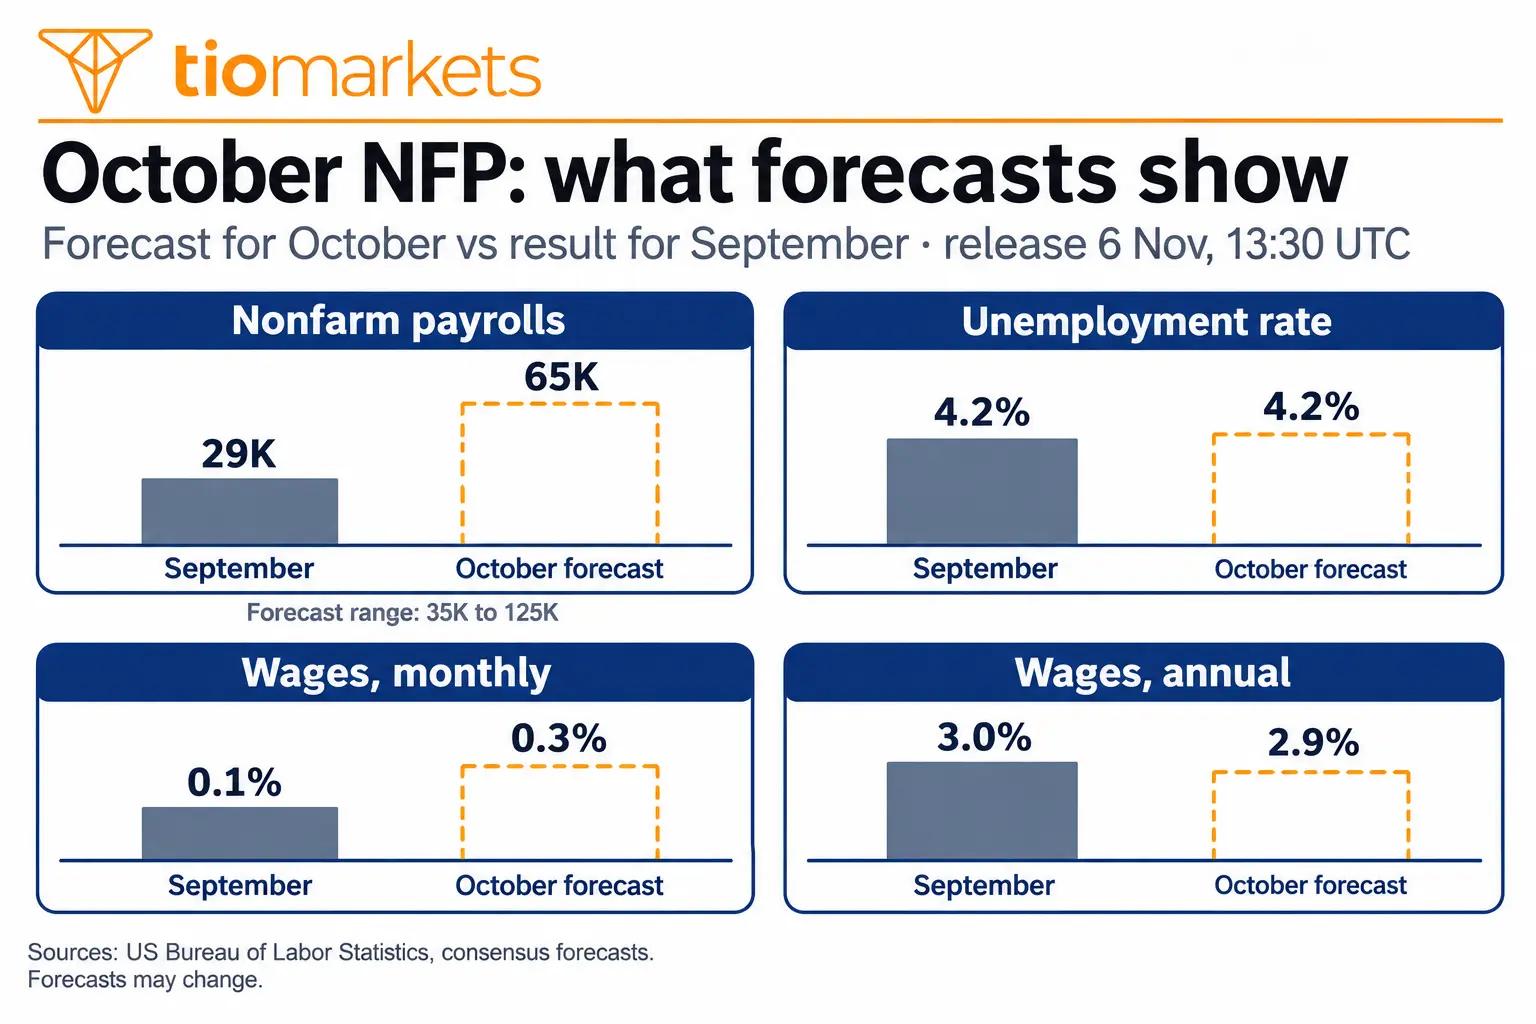
- Forecasts point to around 65,000 new jobs, within a range of roughly 35,000 to 125,000, after 29,000 in September.
- Unemployment is expected to stay at 4.2%, while annual wage growth is forecast to slow to 2.9% from 3.0%.
- The Fed held its rate at 3.75%–4.00% on 28 October in a 10–2 vote, with two officials preferring a rise.
- Gold has recovered back above $4,000 after dipping toward $3,890 in late October, while EUR/USD has been trading in the upper half of its October range, above 1.1200.
What is the NFP report and when is it released?
The nonfarm payrolls report, often called the NFP, measures how many jobs the US economy added or lost in the previous month, excluding farm workers, private household staff and some non-profit roles. It is published by the Bureau of Labor Statistics together with the unemployment rate and average hourly earnings, which show how fast wages are rising.
Because jobs and wages shape the Fed's decisions on interest rates, the NFP is one of the most market-moving data releases of the month. The October report is due at 13:30 UTC on Friday 6 November, as shown on our economic calendar.
What the forecasts show for October nonfarm payrolls
| Indicator | Forecast (October) | Previous (September) |
| Nonfarm payrolls | About 65,000 | 29,000 |
| Unemployment rate | 4.2% | 4.2% |
| Average hourly earnings, monthly | 0.3% | 0.1% |
| Average hourly earnings, annual | 2.9% | 3.0% |
Forecasts vary by source and may change before the release.
In simple terms: forecasters expect hiring to pick up a little from September's very weak figure, but still at a slow pace compared with earlier in the year. A figure near the forecast would point to a labour market that is cooling gradually rather than falling sharply.
Why this NFP report matters for the Fed
The September report was a clear disappointment. Payrolls rose by only 29,000, well below forecasts of around 90,000, and the figures for July and August were revised down by a combined 60,000. Unemployment rose to 4.2% from 4.1%, and annual wage growth slowed to 3.0%. Our previous NFP preview covers that release in more detail.
The Fed is balancing that weaker jobs picture against inflation that remains well above its 2% target. It raised rates in September, then held them at 3.75%–4.00% on 28 October, with two officials voting for a further rise. Its statement did not commit to a move in December, and Chair Kevin Warsh has said he prefers not to signal the future path of rates. Our Fed interest rate decision preview explains the background.
That makes this NFP report important for December. Stronger-than-expected hiring could strengthen the case for another rise, while a second weak month could make the Fed more cautious.
Four things to watch in the NFP report
1. The headline payrolls number
The number of new jobs is the figure markets react to first. A result well above or below the forecast range is likely to cause the biggest moves.
2. The unemployment rate
A rise to 4.3% or above would suggest the labour market is weakening faster, even if payrolls look acceptable.
3. Wage growth
Average hourly earnings show whether rising wages could keep inflation high. Faster wage growth than expected would be a concern for the Fed, while slower growth would ease that worry.
4. Revisions to earlier months
Large downward revisions to September or August, as happened last month, can change how markets read the whole report.
How the NFP report could move gold
Gold tends to react to the jobs report through its effect on US interest rate expectations and the dollar. Stronger data can lift yields and the dollar, which often weighs on gold because it pays no interest, while weaker data can have the opposite effect.
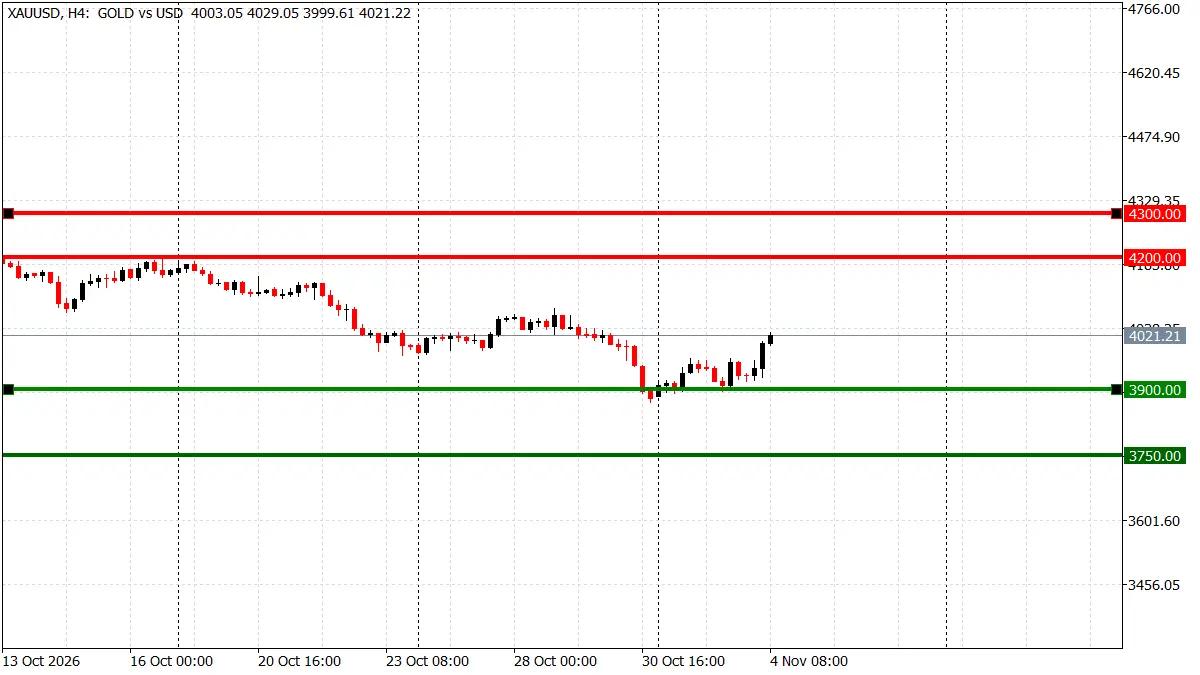
Gold traded mostly between $4,100 and $4,250 from late September to mid-October, then slipped below $4,000 in late October, briefly dipping toward $3,890, before recovering back above $4,000 in early November. Gold has been trading in a broad 3,750–4,300 range. Reference levels traders are watching:
- $4,300: the round-number resistance above the October highs
- $4,200: the top of the October range
- $3,900: the late-October low area
- $3,750: the next support area below
A stronger-than-expected report could push gold toward $3,850 and $3,750. A weaker-than-expected report could support a rebound toward $4,100 and $4,300.
How the NFP report could move EUR/USD
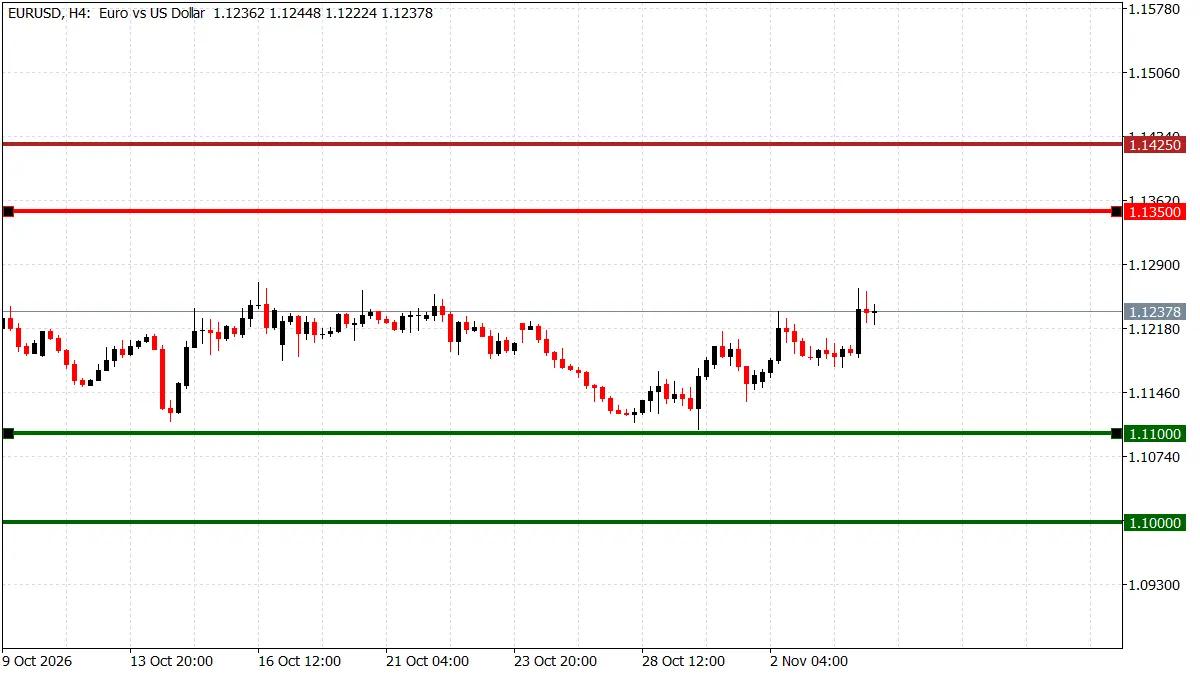
EUR/USD shows how many US dollars one euro buys, so a falling pair means a stronger dollar. The pair has traded mostly between 1.1100 and 1.1300 since early October, dipping toward 1.1100 in late October before recovering above 1.1200 in early November. The European Central Bank kept its deposit rate at 2.50% on 29 October, so US data have been a key driver of the pair. Our ECB rate decision preview covers the euro side.
EUR/USD has been trading in a broad 1.1000–1.1425 range. Reference levels traders are watching:
- 1.1425: the late-September resistance area
- 1.1300: the top of the October range
- 1.1100: the first support area below the October lows
- 1.1000: the round-number support area
A stronger-than-expected report could lift the dollar and push EUR/USD toward 1.1100 and 1.1000. A weaker-than-expected report could lift the pair toward 1.1300 and possibly 1.1425.
All levels are context markers, not entry or exit points, and should be checked against a live price feed.
Trade Gold and EUR/USD with TIOmarkets
Take your position on major currencies and metals via CFDs. Enjoy tight spreads, fast execution, and fast, flexible funding options.
Trading is risky
Three scenarios: better than expected, as expected or worse than expected
In this table, "better than expected" means more jobs and a lower unemployment rate than forecast, and "worse than expected" means fewer jobs and a higher unemployment rate. A better-than-expected report tends to support the US dollar, which often means a lower gold price and a lower EUR/USD.
| Scenario | What it could look like | Possible market reaction | What could change the reading |
| Better than expected | Payrolls above about 125,000, the top of the forecast range, and unemployment at 4.1% or lower | The dollar and US yields could rise as expectations of a December rate rise grow; gold could fall toward 3,950–3,750 and EUR/USD toward 1.1100–1.1000 | Large downward revisions to earlier months, or wage growth slower than expected |
| As expected | Payrolls roughly between 35,000 and 125,000, with unemployment at 4.2% and wage growth near forecasts | First moves may be limited; gold could stay within 3,850–4,100 and EUR/USD within 1.1100–1.1300 as attention shifts to US inflation data the following week | The details: unemployment, wages and revisions |
| Worse than expected | Payrolls below about 35,000 or negative, and unemployment at 4.3% or higher | The dollar and US yields could fall as expectations of a December rise fade; gold could rebound toward 4,100–4,300 and EUR/USD toward 1.1300–1.1425 | Wage growth faster than expected, or upward revisions to earlier months |
Scenario thresholds are editorial guideposts, not forecasts or trading recommendations.
A mixed report may create the hardest reaction
The most difficult outcome to read is a mixed report, for example more jobs than expected but higher unemployment, or strong hiring alongside much slower wage growth. In that case, the first move in the dollar may reverse as traders look at all the details together. Liquidity can thin around 13:30 UTC, which can widen spreads and cause slippage.
Key events to watch
- Wednesday 4 November, 13:15 UTC: ADP private payrolls for October
- Friday 6 November, 13:30 UTC: US nonfarm payrolls, unemployment and wages for October
- Next week: US consumer price inflation for October
- Wednesday 9 December: the next Fed rate decision
- Thursday 17 December: the Bank of England and ECB rate decisions
Risks and uncertainties
Jobs data can be noisy from month to month, and revisions can change the picture significantly. Oil prices remain highly sensitive to developments in the Middle East, and a sharp move in energy could change the inflation outlook, and with it the Fed's view, regardless of the jobs data. Other events, including the US inflation report the following week, can quickly outweigh the market's first reaction to the NFP.
Market direction is not mechanical. Positioning, liquidity and global risk sentiment can outweigh the usual relationship between jobs data and individual assets, and prices can gap or reverse rapidly around the release.
Conclusion
The October NFP report is expected to show a modest recovery in hiring to around 65,000 after September's 29,000, with unemployment holding at 4.2%. Because the Fed is weighing slower job growth against high inflation, the report could shape expectations for its December meeting. A stronger result could support the dollar and weigh on gold and EUR/USD, while a second weak month could do the opposite. The details, especially unemployment, wages and revisions, may matter as much as the headline number.
FAQ
Risk disclaimer: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money. Never deposit more than you are prepared to lose. Professional client’s losses can exceed their deposit. Please see our risk warning policy and seek independent professional advice if you do not fully understand. This information is not directed or intended for distribution to or use by residents of certain countries/jurisdictions including, but not limited to, USA & Countries included in the OFAC sanction list. The Company holds the right to alter the aforementioned list of countries at its own discretion.
TIOmarkets offers an exclusively execution-only service. The views expressed are for information purposes only. None of the content provided constitutes any form of investment advice. The comments are made available purely for educational and marketing purposes and do NOT constitute advice or investment recommendation (and should not be considered as such) and do not in any way constitute an invitation to acquire any financial instrument or product. TIOmarkets and its affiliates and consultants are not liable for any damages that may be caused by individual comments or statements by TIOmarkets analysis and assumes no liability with respect to the completeness and correctness of the content presented. The investor is solely responsible for the risk of his/her investment decisions. The analyses and comments presented do not include any consideration of your personal investment objectives, financial circumstances, or needs. The content has not been prepared in accordance with any legal requirements for financial analysis and must, therefore, be viewed by the reader as marketing information. TIOmarkets prohibits duplication or publication without explicit approval.
Join us on social media


Authors BIO
An experienced financial analyst and educator with over 8 years of expertise covering gold, forex, and global financial markets. Ahmed specializes in blending price action analysis with macroeconomic data to accurately interpret market movements, providing readers with comprehensive educational insights into trading and the financial world.





